Licensed | Insured | Family Owned
(818) 275-0921 CALL NOW · OPEN 7 DAYS
INSURANCE CLAIM ASSISTANCE
Get a FREENEW ROOFAlmost for Free!
Your Insurance May Cover the Cost
If your home has wind, storm, or weather-related damage,
you may qualify for a full roof replacement with only your
deductible. We handle the entire insurance claim process
from inspection to final installation.
- INSPECTION
& PHOTOS - CLAIM
SUPPORT - MAXIMUM
COVERAGE - EXPERIENCED
TEAM - NO OUT-OF-
POCKET SURPRISES



GET A ROOF QUOTE TODAY
RESIDENTIAL • COMMERCIAL • ALL ROOF TYPES
- LICENSED
& INSURED - FAST
RESPONSE - EXPERIENCED
ROOFERS - QUALITY
WORKMANSHIP
BUILT FORSouthern California
STORM DAMAGE HAPPENS
Protect Your Home
After the Storm
High winds, heavy rain, and severe weather can cause
missing shingles, lifted shingles, cracked shingles, and
other damage that may qualify for an insurance claim.
Don’t wait — get your roof inspected before small issues
turn into big, expensive problems.
 LIFTED SHINGLES
 MISSING SHINGLES
 STORM DAMAGE
 CRACKED SHINGLES
A STRONGER HOME
STARTS HERE.
Trusted. Proven. Owens Corning.
WHY CHOOSE US?
-
INSURANCE CLAIM EXPERTSWe know the process and work with all major insurance carriers.
-
DETAILED DOCUMENTATIONHigh-resolution photos, measurements, and professional reports.
-
WE MEET WITH YOUR ADJUSTERWe work directly with your insurance adjuster to ensure all damage is properly documented.
-
QUALITY ROOF REPLACEMENTSWe install Owens Corning shingles with industry-leading warranties.
-
A SMOOTH, STRESS-FREE PROCESSWe handle the paperwork so you can focus on what matters.
PREMIUM OWENS CORNING SHINGLE OPTIONS
Beauty. Performance. Peace of Mind.
Choose from a wide range of Owens Corning shingles designed for long-lasting protection and curb appeal.
 Onyx Black
 Sierra Grey
 Driftwood
 Sandcastle
 Estate Gray
MORE
THAN JUST
A ROOF.
A BRIGHTER
TOMORROW.®
HOW THE INSURANCE CLAIM PROCESS WORKS
We Handle the Details So You Don’t Have To.
- 1 FREE INSPECTIONWe inspect your roof for storm or wind damage and provide a detailed report with photos.
- 2 FILE YOUR CLAIMWe help you file your claim and provide all necessary documentation.
- 3 MEET WITH ADJUSTERWe work directly with your insurance adjuster to ensure all damage is properly documented.
- 4 CLAIM APPROVALOnce approved, your insurance covers the roof replacement (minus your deductible).
- 5 NEW ROOF INSTALLATIONWe install your new, high-quality Owens Corning roof with professional craftsmanship and warranty.
WE WORK WITH ALL MAJOR INSURANCE COMPANIES
INCREASE YOUR HOME’S VALUE
WITH A NEW ROOF
Protection, beauty, and peace of mind.
DON’T WAIT UNTIL MORE DAMAGE OCCURS
See If You Qualify Today!
Your homeowners insurance may cover the cost of a new roof.
Get a free inspection and let our team handle the rest.
No obligation. Just honest answers.
- LICENSED & INSURED
- EXPERIENCED ROOFERS
- HIGH-QUALITY MATERIALS
- PROUDLY SERVING
SOUTHERN CALIFORNIA
FREE ROOF PROGRAM SAN DIMAS, CA
STORM DAMAGE CLAIMS IN SAN DIMAS AND WHAT THEY COVER
The roofs we end up replacing through insurance in San Dimas usually looked fine from the street the week before. hillside lots take the Santa Ana winds first and hold afternoon sun longer than the flats.
What carriers actually cover
Whether a roof qualifies comes down to what caused the damage and when.
- A recent date of loss. Most policies expect the claim to be filed within a set window of the event, so a wind event you remember is worth acting on.
- Sudden, identifiable damage. Wind, hail, falling branches and storm debris are covered events. Gradual wear and age are not.
- Damage the adjuster can see. Lifted or creased shingles, broken seals, displaced ridge caps, damaged flashing — documented slope by slope.
- An active policy with roof coverage. Replacement cost policies pay differently than actual cash value, and it's worth knowing which you have before the call.
The honest version
Not every roof qualifies. Plenty of the roofs we look at in San Dimas are simply worn out, and age is not a covered peril — in that case we'll quote the replacement and talk financing instead.
What we handle, step by step
- Free inspection. We photograph every slope, including drone imagery, and tell you plainly whether there's a claim worth filing.
- Documentation. You get a written report with dated photos, the kind of package an adjuster expects to receive.
- You file the claim. The policy is yours, so the claim is yours. We supply the evidence.
- We meet the adjuster. On the roof, at your property, so nothing gets missed on the walkthrough.
- Approval and scope. If items are left off the scope, we supply the detail for a supplement or re-inspection.
- Replacement. Tear-off to bare deck, new underlayment and flashing, new shingles, full cleanup and a photo walkthrough.
What the weather does here
Steeper pitches, longer rakes and open exposure mean wind uplift and UV are the two things that age a roof here in San Dimas. Hillside lots take the Santa Ana winds first and hold afternoon sun longer than the flats, and that is exactly the kind of sudden damage a policy is written for. Most of the claims we document here start at a rake, a ridge line or a piece of flashing.
What you actually pay
We don't waive deductibles or inflate a scope. That's insurance fraud, it's illegal in California, and it puts your policy at risk as much as our license.
Your deductible is the number that matters. If the repair costs less than the deductible, we'll tell you not to file — a claim on the record with no payout helps nobody.
Serving San Dimas and nearby
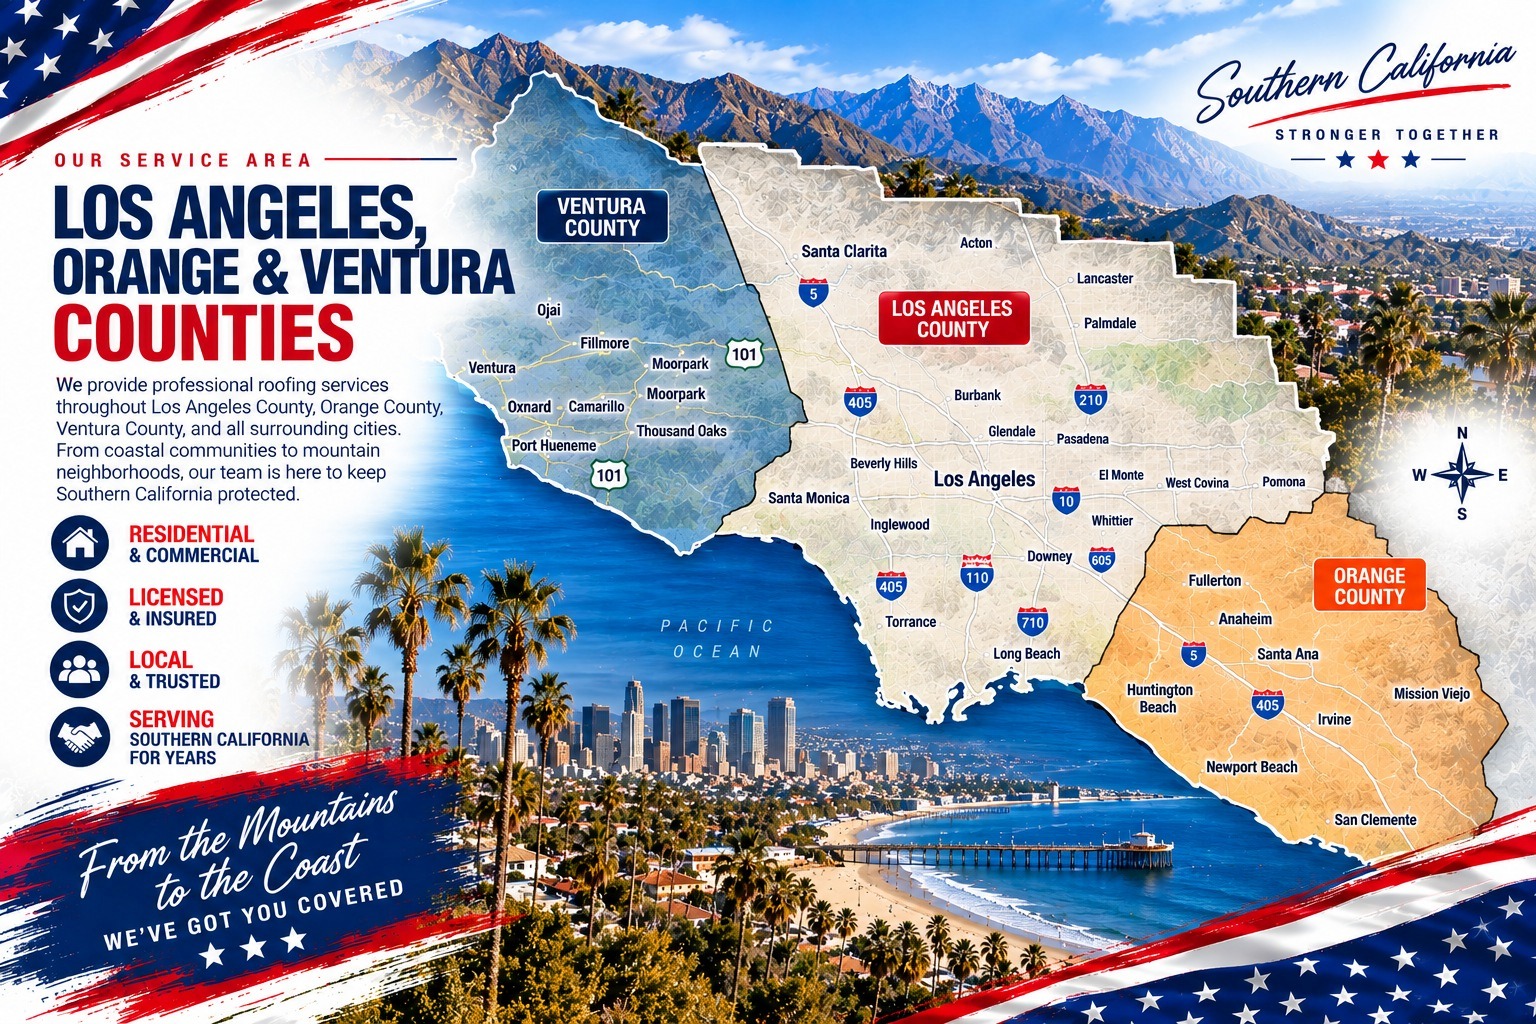
We handle storm damage claims and full replacements throughout San Dimas and the surrounding Los Angeles County communities, including La Verne, Glendora and Pomona.
Book a free inspection
The inspection is free and there is no obligation. Call (818) 275-0921 and we will photograph every slope of your San Dimas roof and tell you plainly whether a claim is worth filing.
What changes on a San Dimas roof
Roof life in San Dimas is decided by exposure more than brand, and sun on the exposed slopes dries out the cheap underlayments early. San Dimas is around 25 miles east of the shop, which keeps scheduling simple.
La Verne, Glendora and Pomona are on the same route, which keeps follow-ups easy.
- We work around tenants and business hours where the building is occupied.
- We protect landscaping and the pool before a single bundle comes off the truck.
- Dry-in happens the same day the old roof comes off; nothing sits open overnight.
- Gutters are pulled and refitted where they block a proper drip edge.
- Solar panels get detached and reset on a schedule that matches the roofing crew.
Scheduling before the rains means the whole job happens on dry decking. You get photos, measurements and a plain explanation before any work is booked.
What separates a good job from a cheap one
We do not ask for large deposits before material is delivered.
- We check the attic as well as the roof; half of what we find shows from underneath.
- Synthetic underlayment goes down over the whole deck, not just the valleys.
- You get a text when the crew is coming and a walk-through when they are done.
- Weather delays are called early rather than left to surprise you.
FREQUENTLY ASKED
QUESTIONS
Find answers to common questions about free roof program in San Dimas.
CLEAR ANSWERS. LOCAL EXPERTISE.
SAN DIMAS, CA FREE ROOF PROGRAM
Can you work around solar panels?
Yes. Panels are detached and reset on a schedule that matches the roofing crew, and the penetrations are re-flashed properly when they go back.
How long do I have to file after a storm?
Most policies set a deadline, and waiting can cost you the claim. If a storm has come through San Dimas, get the roof looked at now.
How long does the work take?
Most single-family roofs in San Dimas are done in two to four days once materials are on site. Larger or steeper roofs, or jobs with deck repairs, run longer and we say so up front.
Do you pull permits in San Dimas?
We do. Permits and inspections go through the local building department and we handle the paperwork rather than leaving it to you.
Will you meet my insurance adjuster in San Dimas?
Yes. We are on the roof with the adjuster, pointing out every damaged area so nothing is missed in the scope.
Does my San Dimas home qualify for a new roof through insurance?
If the damage traces back to a specific wind or storm event, is spread across the roof and your policy was active at the time, it is worth filing. The inspection tells you before you call the carrier.
Are you licensed and insured?
Yes, licensed, bonded and insured, with workers' compensation on every crew. Certificates are available before work starts.
Do I pay anything if the claim is approved?
You pay your deductible. We never offer to cover, waive or absorb it, because that is insurance fraud and it puts your claim at risk.